What Is US Worker Classification?
US Worker Classification is an important part of running a business in the United States. Employers must determine whether a person is an employee or an independent contractor because each category has different tax and reporting requirements.
For example, employers generally withhold federal income tax, Social Security tax, and Medicare tax from employee wages. They must also report certain payments to nonemployee workers. Therefore, choosing the correct worker category helps businesses avoid tax errors and compliance problems.
Common worker categories in the United States include:
- Employee: A person who works under an employer-employee relationship.
- Independent Contractor: A self-employed person who provides services to a business.
- Statutory Employee: A worker who qualifies for employee treatment under specific federal tax rules.
- Statutory Nonemployee: A worker who qualifies for special tax treatment under federal law.
This guide explains the main differences between these categories, their tax responsibilities, and the rules for hiring family members.
US Worker Classification: Employee vs. Independent Contractor
The first step is to determine whether a worker is an employee or an independent contractor. This decision affects payroll taxes, tax forms, and the employer's reporting duties.
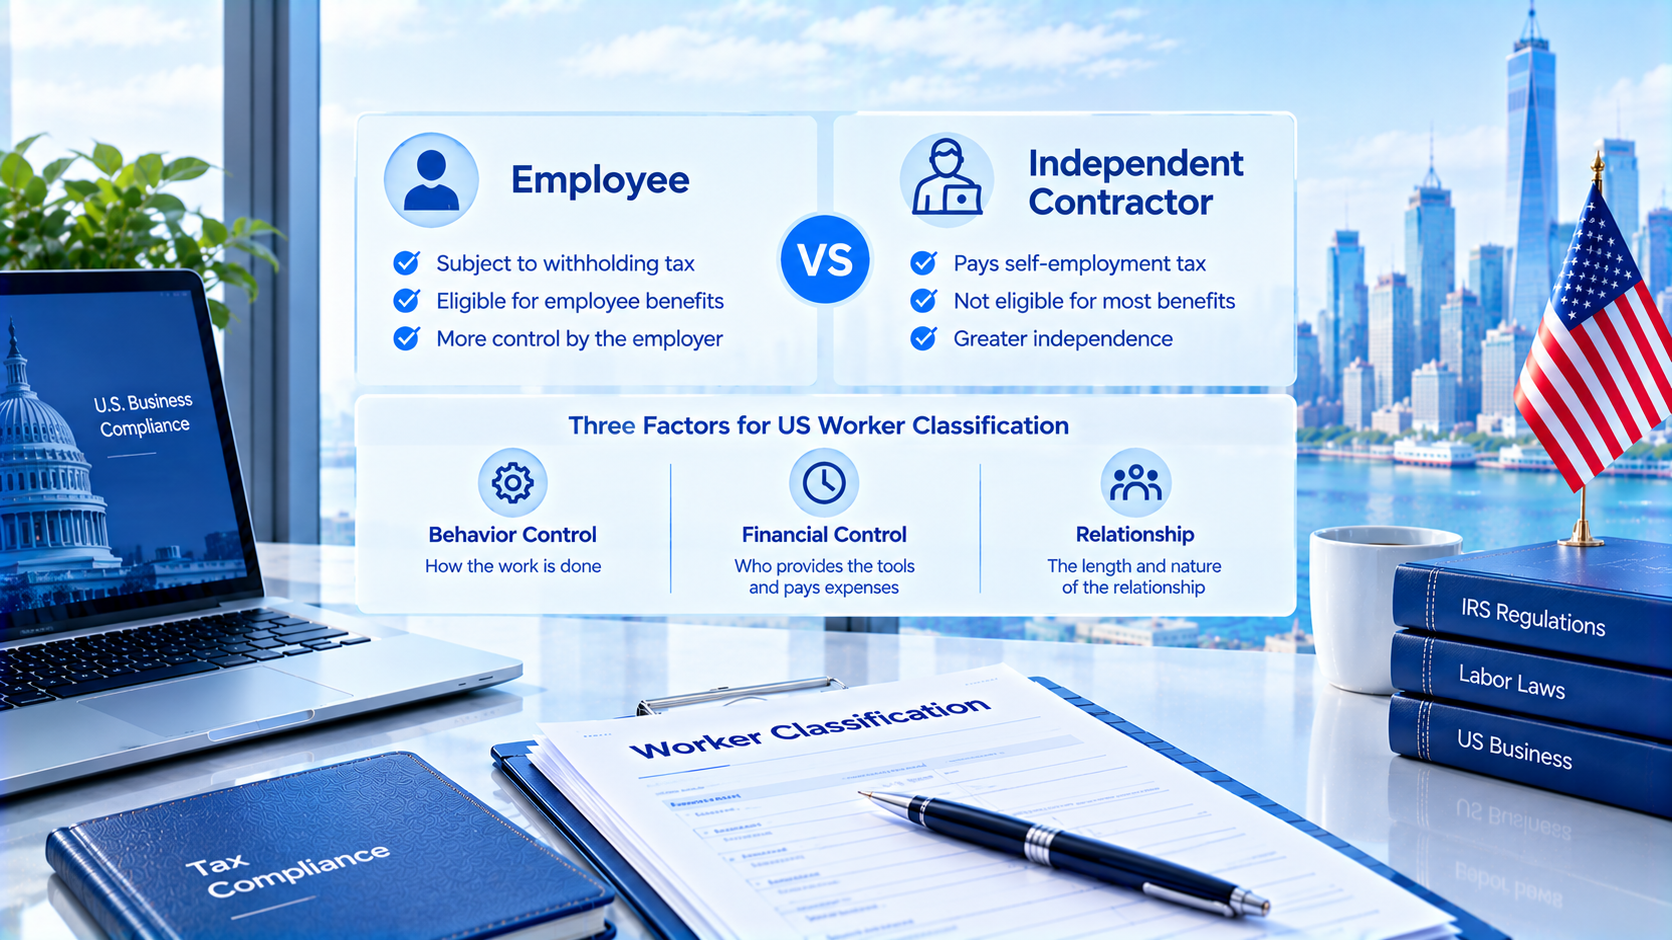
Three Factors for US Worker Classification
The IRS reviews the facts of each working relationship and generally groups them into three categories.
| Factor | What to Consider |
|---|---|
| Behavioral Control | Does the business control, or have the right to control, how the worker performs the job? |
| Financial Control | Does the business control payment methods, expense reimbursement, tools, supplies, or other business arrangements? |
| Type of Relationship | Is there a written contract? Does the worker receive employee benefits? Does the relationship suggest long-term employment? |
No single factor automatically determines a worker's status. Instead, the IRS considers the overall relationship and the degree of control and independence.
Importantly, a contract that labels someone an independent contractor does not settle the issue. If the actual working relationship meets the legal definition of employment, the business may still need to treat that person as an employee.
For more information, see the IRS guide to employee and independent contractor classification.
US Worker Classification: Tax and Reporting Requirements
Employees and independent contractors have different tax responsibilities. The following table summarizes the main differences.
| Requirement | Employee | Independent Contractor |
|---|---|---|
| Federal income tax | Employer generally withholds tax based on Form W-4 | Contractor generally manages their own income tax |
| Social Security and Medicare | Employee and employer generally each pay 6.2% Social Security tax and 1.45% Medicare tax, subject to applicable rules and limits | Contractor generally pays self-employment tax when the rules apply |
| Federal unemployment tax (FUTA) | Employer generally pays applicable FUTA tax | Generally does not apply to payments for services by a genuine independent contractor |
| Main tax form | Form W-2 | Form 1099-NEC may be required |
| Income reporting | Employee reports wages on their tax return | Self-employed individual generally reports business income and expenses on Schedule C, when applicable |
For employees, employers use Form W-4 and any applicable state withholding forms to calculate payroll withholding. They must also pay their share of Social Security and Medicare taxes. In addition, federal unemployment tax and state-level payroll obligations may apply.
Employers generally must provide Form W-2 to employees by January 31 of the following year, subject to the applicable filing rules.
Independent contractors usually manage their own income tax and business expenses. If a contractor has net earnings from self-employment of $400 or more, they generally need to consider self-employment tax when the rules apply. Schedule C helps them report business income and expenses, while Schedule SE generally calculates self-employment tax.
For payments made in 2026, businesses generally must file Form 1099-NEC when reportable payments for services to a nonemployee reach $2,000 or more during the calendar year. The general threshold was $600 for payments made before 2026. Businesses generally must provide the form to the recipient and file it with the IRS by January 31, subject to applicable filing rules.
US Worker Classification and Payments to Foreign Contractors
International businesses should not assume that payments to foreign contractors follow the same rules as payments to U.S. contractors. Backup withholding and nonresident alien withholding depend on the payee's tax status, the type and source of income, and other applicable rules.
For example, a business may need to review whether a foreign individual performs services inside or outside the United States and whether the payment qualifies for specific tax treatment. Businesses should check the relevant IRS requirements before deciding whether to withhold tax or file an information return.
US Worker Classification: Statutory Employees and Nonemployees
Some workers fall into special categories under federal tax law. These categories do not apply to every employee or contractor; each has specific legal requirements.
Statutory Employees
A statutory employee qualifies for employee treatment for certain federal employment tax purposes, even though the working arrangement may have features of self-employment.
When the rules apply, the employer generally issues Form W-2 and checks the Statutory Employee box in Box 13. The employer handles Social Security and Medicare taxes under the applicable rules, while federal unemployment tax treatment depends on the circumstances.
For individual income tax reporting, a statutory employee generally reports the related income and business expenses on Schedule C. The worker should follow the IRS instructions for their specific situation because statutory employee income follows different rules from ordinary employee wages.
Statutory Nonemployees
Federal law recognizes three main categories of statutory nonemployees:
- Direct sellers who meet the applicable requirements
- Licensed real estate agents who meet the applicable requirements
- Certain companion sitters
For direct sellers and licensed real estate agents, payments must generally depend on sales or other output rather than hours worked. In addition, a written contract must state that the worker will not qualify as an employee for federal tax purposes.
Qualifying statutory nonemployees generally count as self-employed for federal tax purposes. They may receive Form 1099-NEC when the reporting requirements apply and generally report business income and expenses on Schedule C.
Companion sitters follow separate rules. A sitter who does not work for a placement service may still qualify as an employee of the person receiving the services. The actual working relationship and household employment rules determine the result.
Therefore, businesses should review the relevant IRS guidance rather than assume that every sales-based worker or caregiver qualifies as a statutory nonemployee.
US Worker Classification: Hiring Family Members
Hiring family members can create different employment tax obligations. The rules depend on the family relationship and the legal structure of the business.

When Parents Hire Their Children
When a parent employs their child in a sole proprietorship, or in a partnership where every partner is the child's parent, special federal employment tax rules may apply.
| Child's Age | Social Security and Medicare Taxes | FUTA |
|---|---|---|
| Under 18 | Generally exempt | Generally exempt if under 21 |
| 18–20 | Generally apply | Generally exempt |
| 21 or older | Generally apply | Generally apply |
Wages may still require federal income tax withholding, regardless of the child's age.
However, if a corporation employs the child, the family-based exemptions generally do not apply. The same generally holds for a partnership where not every partner is the child's parent. In these situations, the business may need to handle income tax withholding, Social Security tax, Medicare tax, and FUTA under the usual rules.
When One Spouse Hires the Other
If one spouse employs the other in a sole proprietorship, the wages generally require federal income tax withholding, Social Security tax, and Medicare tax. However, the business generally does not pay FUTA on those wages.
A corporation follows different rules. When a corporation employs a spouse, the usual family-based FUTA exemption generally does not apply, and the business must follow the relevant employment tax rules.
A business run by both spouses may receive different tax treatment if their arrangement qualifies as a partnership or a qualified joint venture. Therefore, business owners should review their structure and the actual working relationship before deciding which filing requirements apply.
For further details, see the IRS guidance on family employees.
How IngStart Can Help With US Business Compliance
For international entrepreneurs, hiring workers in the United States involves more than choosing between an employee and an independent contractor. Businesses may also need to manage company registration, EIN applications, payroll arrangements, tax reporting, and ongoing compliance.
IngStart provides services for international businesses, including U.S. company registration, banking support, tax-related services, and ongoing compliance assistance. These services help business owners organize company administration as their U.S. operations grow.
Conclusion
US Worker Classification affects how a business handles payroll taxes, tax forms, and reporting responsibilities. Employees generally receive Form W-2, while qualifying independent contractors may receive Form 1099-NEC. Statutory employees and statutory nonemployees follow additional rules, and family employment may qualify for certain tax exemptions.
For international business owners, the key is to assess the actual working relationship rather than rely only on a contract or job title. By identifying the correct worker category and reviewing the relevant IRS requirements, businesses can reduce reporting errors and manage their U.S. tax responsibilities more effectively.
Because federal rules and state requirements can differ, always check the latest official guidance before making worker classification or payroll decisions.
Article Recommendations
- US Tax Forms Guide: Complete List of Common IRS Tax Forms
- US Business Tax Compliance Guide: Required Tax Filings & Compliance After Company Formation (2026)
- BVI Tax Residency: Beneficial Owner CRS Guide
If you still have questions, please contact our team on WhatsApp at +1 213 751 2111. We'll help you find the right solution for your business and keep your company compliant as it grows.