
US Securities Tax: What Foreign Investors Need to Know
US Securities Tax rules matter to non-US investors who earn income from American stocks, bonds, and other securities. Depending on the income type and the investor's tax status, the United States may tax the income or require a financial institution to withhold federal income tax.
However, different types of investment income receive different tax treatment. For example, nonresident aliens who meet the relevant conditions generally do not pay US federal income tax on capital gains from selling US stocks. In contrast, US-source dividends usually face withholding tax. Certain interest payments may also qualify for an exemption.
This guide explains the main US Securities Tax rules for foreign investors, when they may claim a tax refund, and how they can prepare a refund request.
US Securities Tax: How to Determine Your Tax Status
Your US tax status helps determine how the IRS taxes your investment income. A non-US citizen does not automatically qualify as a nonresident alien for US tax purposes. Instead, the IRS generally checks whether the individual meets the green card test or the substantial presence test.
The Green Card Test
An individual who holds lawful permanent resident status in the United States generally qualifies as a US tax resident under the green card test. The starting date and tax treatment may depend on when the individual obtained that status and whether special rules apply.
Therefore, foreign investors should not assume that they remain nonresident aliens simply because they hold citizenship in another country.
The Substantial Presence Test
The substantial presence test measures how many days an individual spends in the United States. Generally, an individual must meet both of the following conditions:
- Current-year presence: Spend at least 31 days in the United States during the current calendar year.
- Weighted three-year total: Reach at least 183 days under the following calculation:
| Period | Days counted |
|---|---|
| Current calendar year | 100% |
| First preceding year | 1/3 |
| Second preceding year | 1/6 |
Certain exceptions, treaty rules, and special circumstances may change the result. For this reason, investors should review the IRS rules before determining their tax status.
Read the IRS guidance on taxation of nonresident aliens for more information.

US Securities Tax: How Different Investment Income Is Taxed
For nonresident aliens, the tax treatment of US investment income depends on the income type, the source of the payment, and whether the income connects with a US trade or business.
The following table summarizes common situations. However, the actual treatment may vary according to the investment and the investor's circumstances.
| Investment income | General US federal tax treatment |
|---|---|
| Capital gains from selling US stocks | Generally not taxable, subject to exceptions |
| US stock dividends | Usually 30% withholding, or a lower applicable treaty rate |
| ETF distributions | Depends on the type and classification of the distribution |
| REIT distributions | Depends on the distribution and applicable tax rules |
| Interest from qualifying US bank deposits | Generally exempt for nonresident aliens, subject to exceptions |
| Qualifying portfolio interest from certain bonds | Generally exempt if the requirements are met |
Capital Gains From US Stocks
Nonresident aliens generally do not pay US federal income tax on capital gains from selling US stocks when they meet the relevant conditions. However, exceptions apply. For example, the IRS may tax gains that connect effectively with a US trade or business or arise when the investor meets certain US presence conditions.
Therefore, investors should not assume that every profit from selling a US security is automatically tax-free.
Dividends From US Stocks
US-source dividends paid to nonresident aliens generally face a 30% federal withholding tax. However, an applicable income tax treaty may reduce the rate if the investor meets the relevant requirements.
A valid Form W-8BEN helps the payer or withholding agent confirm the investor's foreign status and apply treaty benefits when the investor qualifies. If the form is missing, expired, or incorrect, the payer may not apply the appropriate withholding rate.
ETF and REIT Distributions
ETF distributions can receive different tax treatment depending on their source and classification. Some distributions may qualify for special treatment, while others may face ordinary dividend withholding rules.
REIT distributions also require careful review. US tax rules may treat different portions of a distribution differently, so investors cannot always determine the tax treatment from the payment amount alone.
Interest From Bank Deposits and Bonds
Qualifying US bank deposit interest generally does not incur US federal income tax for nonresident aliens when it does not connect effectively with a US trade or business. Certain portfolio interest payments on eligible debt obligations may also qualify for an exemption.
Nevertheless, not all interest income is tax-free. Investors should check the type of payment, the relevant requirements, and any applicable treaty provisions.
For more information, see the IRS guidance on US-source income paid to nonresident aliens.
US Securities Tax Refunds: When Can Foreign Investors Claim One?
Foreign investors may qualify for a refund when they pay more US federal income tax than the law requires. This can happen when a withholding agent applies an incorrect rate or fails to apply an available treaty benefit.
However, not every investor who pays withholding tax qualifies for a refund. The applicable tax rules and the investor's circumstances determine the outcome.
Common situations that may justify a refund review include:
- Missing Form W-8BEN: The investor did not provide a valid form in time, so the payer withheld tax without applying an eligible treaty rate.
- Incorrect withholding rate: The broker or withholding agent deducted more tax than the applicable rules required.
- Tax-exempt income: The payer withheld tax from a payment that qualifies for an exemption.
- Incorrect income classification: The final tax treatment differs from the classification the payer used when making the payment.
In some cases, the investor can request an adjustment directly from the broker or withholding agent. In other situations, the investor may need to file a federal tax return with the IRS.
The IRS explains that nonresident aliens generally must file a return to claim a refund of overwithheld or overpaid tax. See its guidance on taxation of nonresident aliens.
US Securities Tax Refund Process: Forms and Documents
Before submitting a refund claim, investors should identify the reason for the overpayment and gather the relevant records. The required documents depend on the income type and the investor's tax situation.
Documents You May Need
Prepare the following documents where applicable:
- Form 1040-NR: The US Nonresident Alien Income Tax Return, which nonresident aliens use when they must file a federal income tax return or claim a refund through a return.
- Form 1042-S: A statement that reports certain US-source income paid to foreign persons and the related withholding.
- Brokerage statements: Records showing investment income, transactions, and tax withheld.
- Identity documents: A passport or other supporting documents, where required.
- Additional evidence: Any treaty-related or other documentation needed to support the claim.
- Form W-7: The application for an Individual Taxpayer Identification Number (ITIN), if the investor needs an ITIN and does not already have one.
A broker may provide other tax statements depending on the account and transactions. For example, Form 1099-B may be relevant in some circumstances, but not every nonresident investor receives this form.
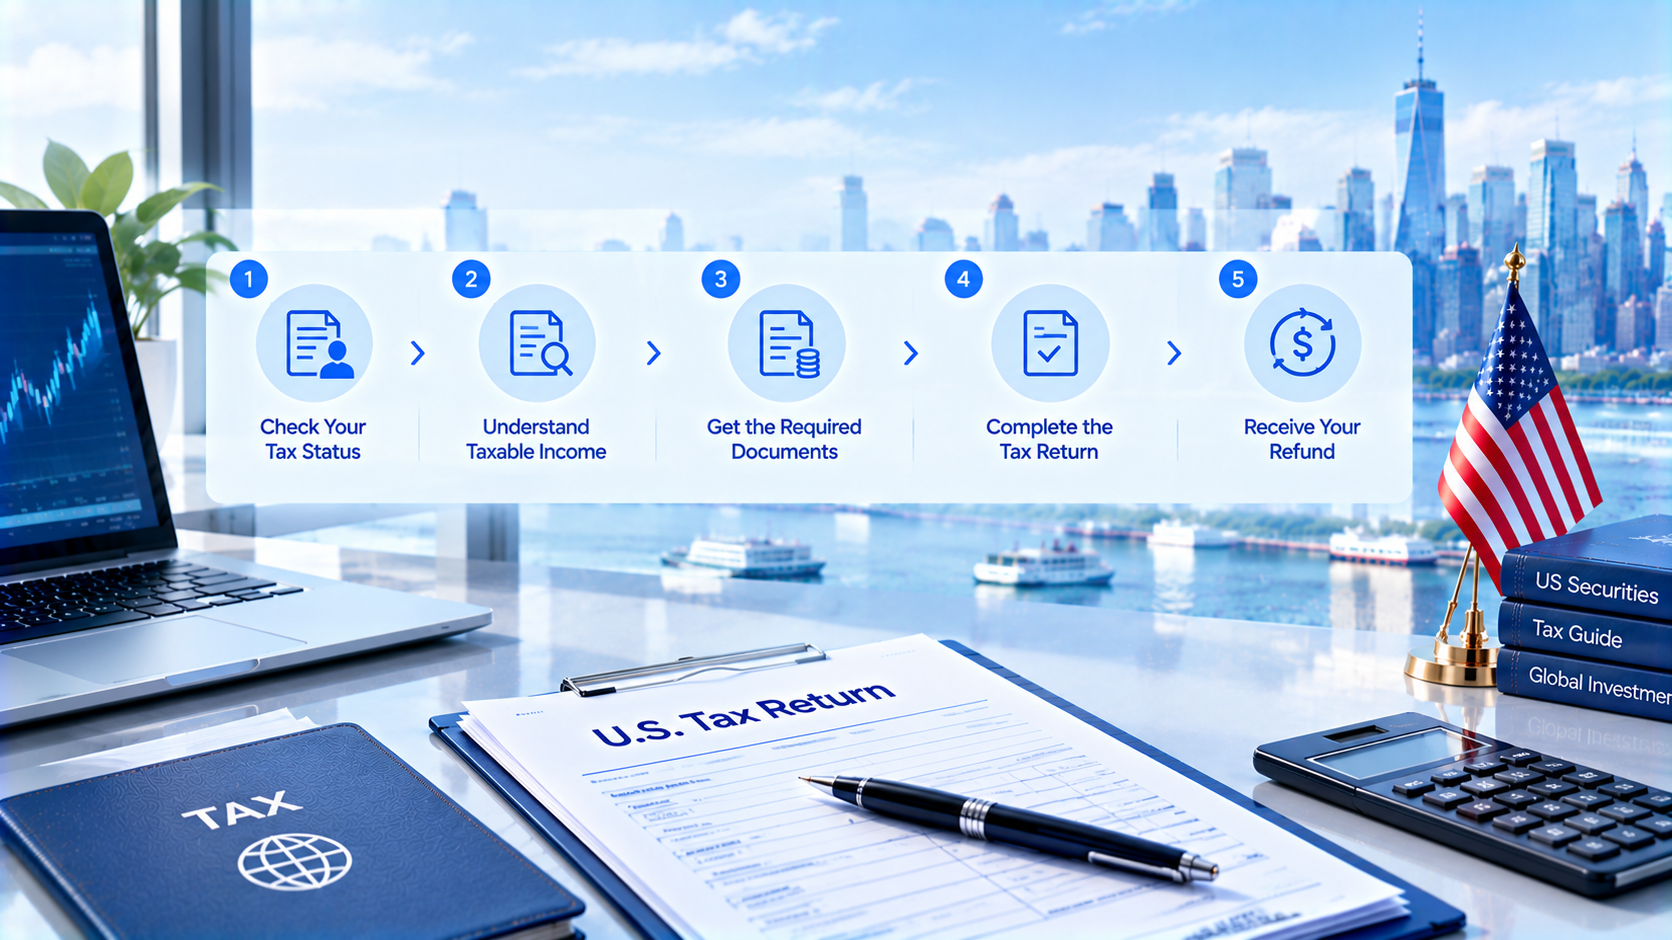
Step 1: Review the Withholding
First, compare your brokerage statements and tax forms with the amount of tax the payer deducted from your investment income. Identify the payment, withholding rate, and reason you believe the amount was incorrect.
Step 2: Confirm Whether You Need an ITIN
If you need to file Form 1040-NR but lack a valid US taxpayer identification number, you may need to apply for an ITIN using Form W-7. Some applicants must submit the W-7 with a federal tax return, while others may qualify for an exception.
An ITIN serves as a tax processing number. It does not give you permission to work in the United States or change your immigration status.
Step 3: Complete the Applicable Tax Return
If you need an IRS return to claim the refund, prepare Form 1040-NR and the relevant schedules. Report your income and withholding correctly, and include the documents that support your claim.
Not every withholding issue follows the same process. Therefore, check the current IRS instructions before submitting your claim.
Step 4: Submit the Application to the IRS
Send the completed return and required supporting documents according to the current IRS filing instructions. Keep copies of your forms, tax statements, and mailing or submission records.
Step 5: Monitor the Refund
The IRS reviews the return and determines whether you qualify for a refund. Processing times vary depending on the application, supporting documents, and IRS workload. The IRS must review and approve the claim before issuing a refund.
US Securities Tax: Important Rules After Filing
Submitting a refund claim is only one part of managing US tax obligations. Foreign investors should also keep their tax documents accurate and monitor deadlines.
Check the Refund Claim Deadline
Under the general federal tax rules, investors usually must claim a refund by the later of three years from the date they filed the tax return or two years from the date they paid the tax. Special rules may apply, particularly when no return was filed or when the claim involves specific types of tax.
As a result, investors should check the applicable deadline rather than assume that they can always correct an old withholding issue.
Keep Your Tax Records
Retain brokerage statements, Forms 1042-S, copies of Form W-8BEN, tax returns, and IRS correspondence. These records can support a refund claim and help you answer questions about your investment income.
You may also need these records when reporting US or foreign investment income in your country of tax residence.
Keep Form W-8BEN Current
Form W-8BEN allows an eligible foreign individual to confirm their foreign status and claim applicable treaty benefits with the withholding agent. The form generally remains valid from the signing date through the end of the third succeeding calendar year, unless a change in circumstances makes the information incorrect. Certain exceptions may apply.
If your tax residency, address, or other relevant details change, inform the withholding agent and provide updated documentation when required. Otherwise, the payer may apply an incorrect withholding rate.
Check Your ITIN Status
An ITIN may expire if you do not use it on a federal tax return for three consecutive tax years. If you need to use an expired ITIN, follow the IRS renewal procedures to avoid possible delays.
For current information, review the IRS guidance on ITIN expiration.
How IngStart Can Support International Investors
Managing US investment taxes can be challenging when you live outside the United States, especially if you also operate an international business. Tax forms, company documents, banking arrangements, and annual compliance may involve different requirements.
IngStart provides services for international entrepreneurs and businesses, including company registration, banking assistance, tax-related services, and ongoing compliance support. These services can help business owners organize their US business administration and prepare relevant documents for professional review.
Conclusion
US Securities Tax rules differ according to the type of investment income and the investor's tax status. Nonresident aliens who meet the relevant conditions generally do not pay US federal income tax on capital gains from US stocks, while US-source dividends usually face withholding tax. Certain bank deposit interest and qualifying bond interest may also qualify for exemptions.
If a broker withholds more tax than required, you may qualify for a refund. Review your payment records, confirm whether you need Form 1040-NR and an ITIN, and submit the appropriate documents within the applicable deadline.
Most importantly, keep Form W-8BEN current and retain your tax records. With proper preparation, foreign investors can better understand their US Securities Tax obligations and avoid missing a valid opportunity to recover overpaid tax.
Article Recommendations
- US Tax Forms Guide: Complete List of Common IRS Tax Forms
- W-7 Form Guide for ITIN Applications: How to Apply for or Renew an ITIN
- W-8 Form Guide for Foreign Taxpayers: A Complete Guide for Foreign Individuals and Businesses
If you still have questions, please contact our team on WhatsApp at +1 213 751 2111. We'll help you find the right solution for your business and keep your company compliant as it grows.